CECL

Ground your CECL allowance in real peer data.

Benchmark your allowance coverage against any peer group, track decades of charge-off history, and document your reserve with the same FFIEC data your examiner reads.

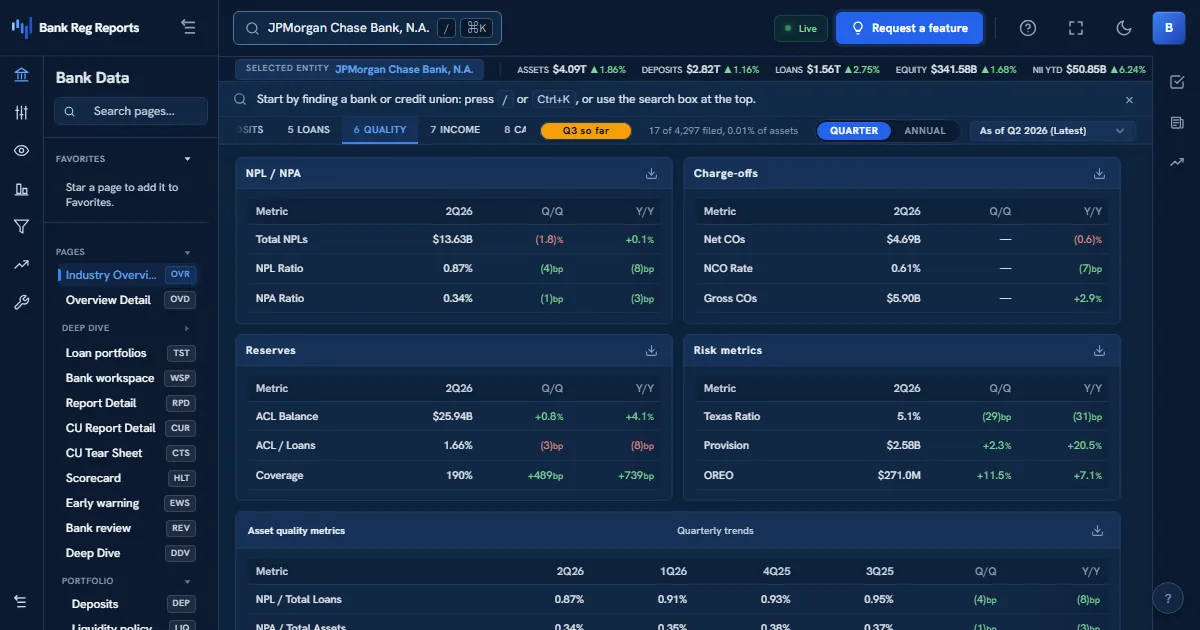
Credit quality screen in the terminal: nonperforming loans, net charge-offs, allowance coverage and ACL to loans by quarter, the loss history that CECL allowance models start from.

What is CECL?

The Current Expected Credit Losses (CECL) standard requires banks to reserve for the lifetime expected losses on a loan from the moment it's originated, rather than waiting until a loss is probable. Phased in for most institutions between 2020 and 2023, it replaced the decades-old incurred-loss model and reshaped how the allowance for credit losses (ACL) is estimated, reported, and examined.

A defensible CECL estimate leans on more than a model output. It needs peer context and a credible loss history. Both live in the FFIEC call report, and both are what BankRegReports makes instantly comparable.

How BankRegReports supports CECL analysis

Allowance coverage benchmarking

Compare your ACL-to-loans coverage against a custom peer group, so you can see whether your reserve is conservative, in line, or light relative to comparable banks.

Decades of loss history

Net charge-off and recovery rates by loan category, quarter by quarter since Q3 2021: the loss experience that anchors a lifetime-loss estimate through a full credit cycle.

Examiner-ready documentation

Export peer comparisons and trend tables that support the qualitative (Q-factor) adjustments and back up your reserve in front of auditors and examiners.

Key metrics for CECL work

Start with the ratios that drive allowance adequacy. Each links to a full definition, formula, and supervisory thresholds in our glossary:

  • Allowance & asset-quality metrics: coverage ratios, noncurrent loans, and net charge-off rates, all defined with worked examples.
  • Peer comparison: benchmark coverage and credit quality against the institutions most like yours.
  • Rankings: see where reserve and credit-quality measures sit across the industry.

How banks use it for CECL

Concrete allowance workflows, from peer benchmarking to examiner-ready documentation.

Benchmark your reserve before the audit

Your external auditor will ask how your allowance compares to peers. You show a defensible, peer-benchmarked coverage ratio instead of a bare model output.

  1. Build a peer group of banks like yours by size, geography, and loan mix.
  2. Compare your ACL-to-loans coverage against the peer median and your percentile.
  3. Export the comparison for the audit file.

Ground a lifetime-loss estimate in real history

A CECL estimate needs a credible loss history across a full cycle, not just recent benign quarters. You pull decades of charge-off experience by loan category to anchor it.

  1. Open net charge-off and recovery rates by loan category.
  2. Review the trend through prior downturns for the segments you hold.
  3. Use the realized loss rates as an input to the lifetime estimate.

Document a Q-factor adjustment for the examiner

A qualitative overlay needs support that traces back to the filing. You back the adjustment with peer and historical data an examiner can verify.

  1. Pull the peer-relative coverage and the relevant loss trend.
  2. Tie the qualitative factor to the observed peer or historical gap.
  3. Attach the sourced comparison to the reserve memo.

CECL questions, answered

What is CECL?

CECL (Current Expected Credit Losses) is the accounting standard, phased in for most banks between 2020 and 2023, that requires institutions to reserve for the lifetime expected losses on a loan at origination rather than waiting for losses to be incurred. It replaced the older incurred-loss model and is reported in the allowance for credit losses (ACL) on the FFIEC call report.

What does CECL stand for?

CECL stands for Current Expected Credit Losses. It is the credit-loss accounting standard (ASU 2016-13, codified in ASC 326) that U.S. banks adopted between 2020 and 2023, replacing the incurred-loss model with a forward-looking, lifetime expected-loss approach.

What is the difference between CECL and ACL?

CECL is the accounting standard (the method for estimating credit losses) while the ACL (allowance for credit losses) is the balance-sheet reserve that the method produces. In short, CECL is how you calculate the number and the ACL is the resulting reserve reported on the call report. The ACL replaced the pre-CECL ALLL (allowance for loan and lease losses).

How does BankRegReports help with CECL?

It lets you benchmark your allowance coverage ratio against any peer group, track your bank's historical net charge-off and loss rates by loan category through past credit cycles, and see how comparable institutions reserve, the context that supports the qualitative (Q-factor) judgment in a CECL estimate and the documentation an auditor or examiner expects.

Where does the allowance and charge-off data come from?

All figures are sourced from FFIEC call reports: the allowance for credit losses, provisions, gross charge-offs, and recoveries that every FDIC-insured bank files quarterly. The methodology for each derived ratio is published in our glossary, so your inputs reconcile to the underlying filing.

How do I benchmark my allowance coverage ratio against peers?

Build a custom peer group (by asset tier, geography, charter, or a hand-picked list) and compare your ACL-to-loans coverage against the peer median and your percentile rank, so you can show whether your reserve is conservative, in line, or light relative to comparable banks.

What historical loss data supports a CECL Q-factor adjustment?

Net charge-off and recovery rates by major loan category, tracked quarter by quarter through prior downturns, give you the realized loss experience that anchors a lifetime-loss estimate and documents a qualitative adjustment with real, sourceable numbers rather than judgment alone.

Which call report line items feed CECL analysis?

The allowance for credit losses (ACL/ALLL), the provision for credit losses, gross charge-offs and recoveries by loan category, and the loan balances they run against: all standardized so coverage, net charge-off, and provisioning ratios are comparable across banks and quarters.
Build a defensible reserve

Peer-benchmarked allowance analysis on every FDIC-insured bank.