Bank Peer Group Analysis: A Step-by-Step Guide
Tell someone a bank has a 3.5% net interest margin and you have told them almost nothing. Is that good? Depends entirely on whether its peers are running 2.9% or 4.2%.
Tell someone a bank has a 3.5% net interest margin and you have told them almost nothing. Is that good? Depends entirely on whether its peers are running 2.9% or 4.2%. Tell them it sits in the 30th percentile of its UBPR peer group and the picture snaps into focus immediately: this bank trails most of its competition on the metric that funds everything else. That is the entire point of bank peer group analysis: it converts isolated figures into judgments by anchoring every metric to the banks most like the one under review.
This guide covers how peer groups are constructed, how to read percentile rankings, when the standard UBPR assignment falls short, and how to build a custom peer group that makes the comparison genuinely revealing. It is the mechanics post. The current community bank benchmark numbers, and the ALCO and exam workflow built on them, live in the companion post on community bank peer benchmarks.
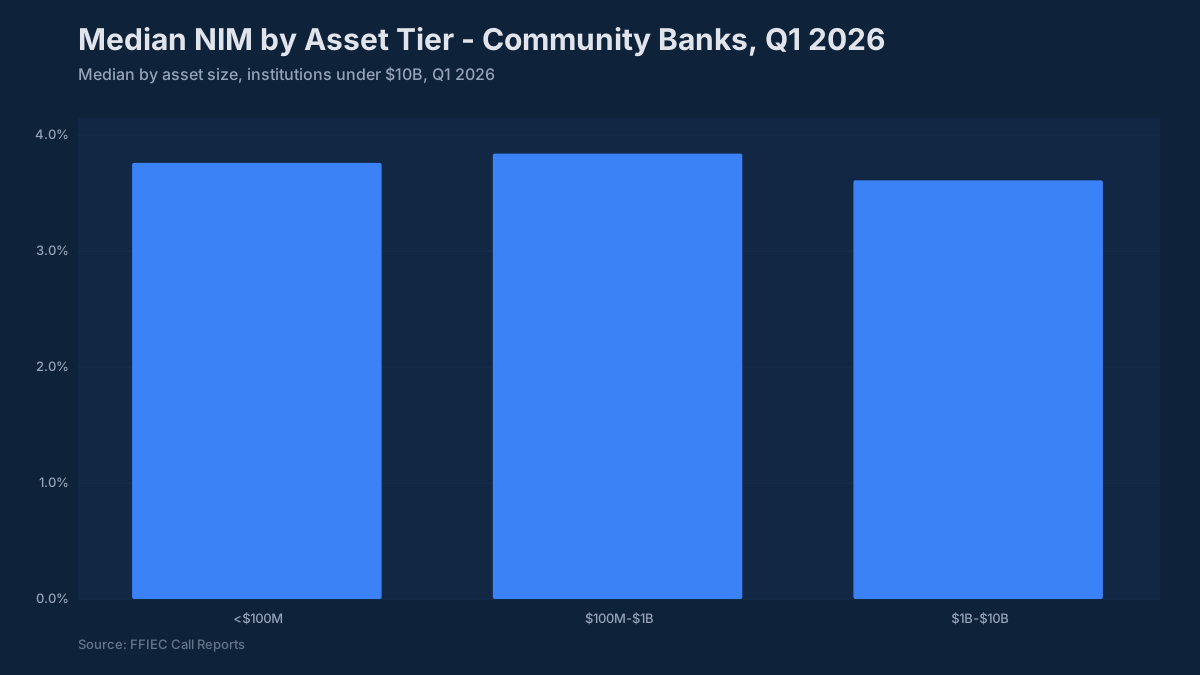
The chart above is why bank peer group analysis exists. Size changes the benchmark: at March 31, 2026, the median NIM ran from 3.85% for $100 million to $300 million banks down to 3.45% for banks above $10 billion, so a 3.7% margin reads differently in each tier.
Why the Right Peer Group Changes the Entire Analysis
Every meaningful question in bank performance is comparative. Is this bank’s efficiency ratio high? Relative to whom? Is its capital strong? Compared to what? A $300 million rural community bank and a $30 billion urban regional bank operate under structurally different economics: deposit costs, loan mix, noninterest income opportunities, and overhead all diverge. Holding them to the same absolute benchmark tells you nothing about performance; it just measures size and business model.
Peer group analysis solves this by comparing each bank only against institutions that share its fundamental characteristics, so differences in the numbers reflect differences in execution, not differences in type.
The data to do this lives in FFIEC call reports: the FFIEC 031 (large banks), FFIEC 041 (larger domestic banks), and FFIEC 051 (domestic banks under $5 billion, which is most community banks). Every metric worth tracking traces back to a specific MDRM code in one of those filings.
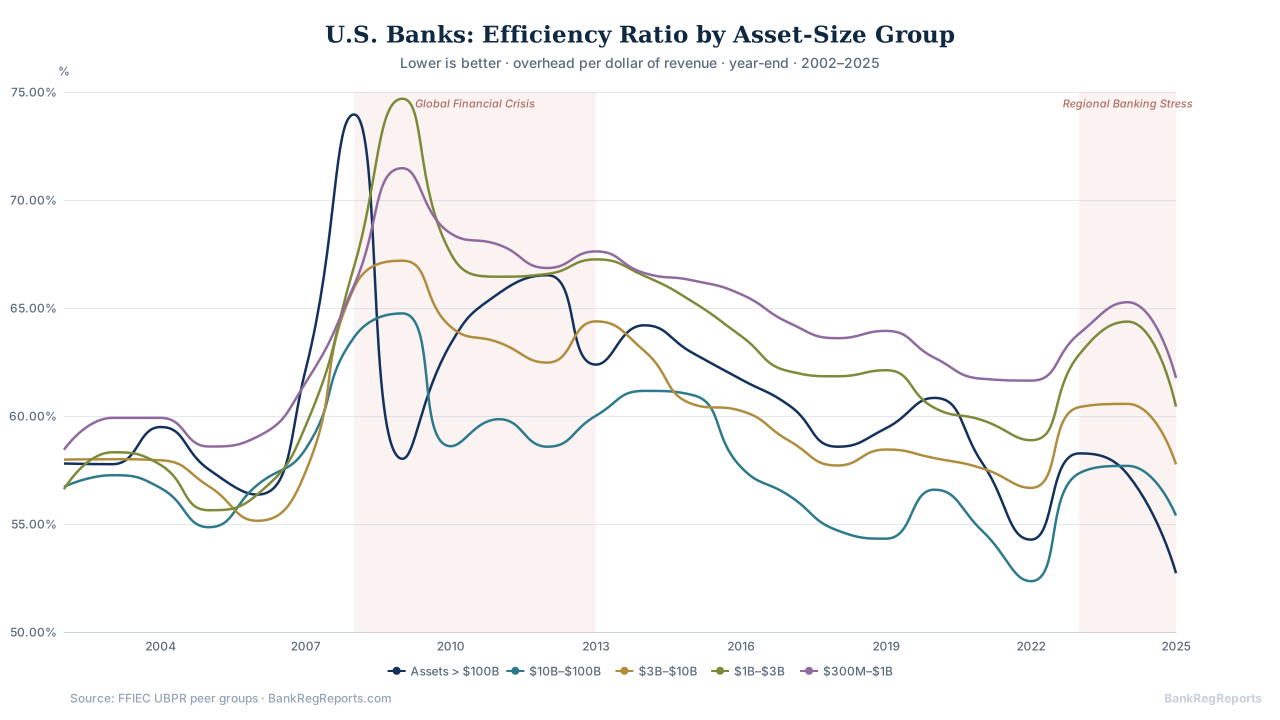
How the UBPR Assigns Peer Groups
The Uniform Bank Performance Report assigns every commercial bank to one of 17 standard peer groups. The assignment logic is straightforward but the implications matter a great deal:
Asset size is the only sort. Since February 26, 2026, the FFIEC assigns commercial banks to peer groups by asset size alone, from Peer Group 1 (above $100 billion) down through bands such as $300 million to $1 billion (Peer Group 5) to the smallest community banks. The basis is average assets for the quarter (RCON3368 on Schedule RC-K of the call report), not period-end total assets (RCON2170). Cross a threshold and your peer group changes, which can shift percentile rankings significantly with no underlying change in performance.
What changed in 2026. Before February 26, 2026, the UBPR also split banks under $300 million by number of banking offices and by metropolitan versus non-metropolitan location. The FFIEC dropped both factors because the resulting groups had become too small to produce reliable averages. Office count and rural or metro location still shape a bank’s economics, which is one reason to build a custom peer group (below).
Once assigned, every ratio in the UBPR appears alongside the peer group average and the bank’s percentile rank within that group. That percentile is where the useful information lives. The raw ratios are context; the percentiles are the verdict.
Reading Percentile Rankings Without Getting Fooled
A percentile ranking tells you where a bank sits in the distribution of its peers. 75th percentile on return on assets means it outperforms three-quarters of comparable banks on that metric. 20th percentile means it trails most of them.
Two things make percentiles more useful than raw ratios. First, they are self-calibrating. When the rate environment compresses margins industry-wide, a bank that holds its 55th percentile NIM ranking is actually performing well; its absolute number fell, but so did everyone else’s. The percentile captures relative performance. Second, they flag outliers instantly. Scanning percentile rankings across the standard ratio categories (capital adequacy, asset quality, earnings, liquidity, sensitivity) takes minutes and surfaces exactly which metrics warrant deeper investigation.
A practical rule that holds up across most cycles: any metric where a bank falls below the 25th percentile or above the 75th deserves a closer look. Low profitability percentiles may indicate operational drag or pricing problems. Anomalously high asset quality percentiles sometimes reflect underreserving rather than clean loans; check the ratio of the allowance (RCON3123) to nonaccrual loans (RCON1403) before concluding a bank’s credit is genuinely superior. High liquidity percentiles can mean excess uninvested cash dragging on earnings.
One note on prefixes before you pull anything. The same call report item carries a different prefix depending on which form the bank files. FFIEC 041 and 051 filers report RCON, for domestic offices. FFIEC 031 filers report RCFD on a consolidated basis, and RCFN for foreign offices, so total deposits for an 031 filer is RCON2200 plus RCFN2200 rather than RCON2200 alone. Schedule RC-R Part I (regulatory capital and the capital ratios) moved off RCON with the Basel III revisions of 2014 and 2015 and now uses RCOA on the 041 and 051 and RCFA on the 031; Part II (risk-weighted assets) still reports under RCON and RCFD. Query a single prefix and you will silently drop a whole population rather than get an error, and for an RCON-only query that population is the largest banks in the country.
When the Standard UBPR Peer Group Is the Wrong Tool
The standard peer group handles most analytical situations. But two banks of nearly identical size can be poor peers if their business models diverge meaningfully. A commercial real estate specialist and a consumer-focused installment lender face completely different credit concentration profiles, interest rate risk exposures, and capital requirements. Averaging their metrics together and calling it a peer group produces a benchmark for neither.
Build a custom peer group when any of the following apply:
Business model mismatch. If the subject bank holds more than 40% of its loan portfolio (RCON2122 from Schedule RC-C) in a single category (CRE, C&I, agriculture, consumer), compare it against banks with similar concentrations. The UBPR peer group average may look fine while hiding that the bank is pricing its niche incorrectly relative to actual competitors.
Geographic competition. For community banks, the relevant competition is often in the same state or metro. Deposit pricing in rural Georgia differs from deposit pricing in suburban Atlanta. A statewide or MSA-filtered peer group captures competitive dynamics that the national size-based assignment misses entirely.
Strategic tracking. Boards and management teams often want to know how they stack up against a specific named set of institutions, not the abstract peer group average. Building and tracking a named competitor panel over time tells a different story than the UBPR percentile, and usually a more useful one.
Threshold distortions. A bank sitting just above a UBPR size cutoff may be compared against institutions twice its scale. Pulling back to a tighter asset band fixes this.
A Step-by-Step Workflow That Holds Up
Start with the standard UBPR peer group for a baseline pass across all ratio categories. Look at capital (Tier 1, CET1), asset quality (NPAs, charge-offs from Schedule RI-B), earnings (ROA, ROE, NIM from net interest income RIAD4074 over average earning assets, UBPR concept UBPRE018, efficiency ratio), and liquidity. Flag anything outside the 25th–75th band.
Then investigate the flagged metrics at the source level, not the UBPR ratio, but the underlying call report schedules. A high NPA ratio could be one large relationship, a portfolio segment, or a classification problem. The UBPR tells you something is off; Schedule RC-N and RI-B tell you what.
Once you have the baseline, ask whether the assigned peer group is actually appropriate for this bank. If the business model or geography makes it a poor fit, rebuild the group. Track percentile trends quarterly, not just point-in-time readings.
The thing most analysts skip: relative position over time. A bank that improves its ROA from 0.85% to 0.95% looks like a turnaround. If its UBPR peer group moved from 0.90% to 1.10% over the same period, that bank is actually losing ground. Absolute trajectory and relative trajectory can point in opposite directions, and only one of them tells you whether management is outperforming its competition.
Frequently Asked Questions
What is bank peer group analysis? The practice of evaluating a bank’s performance by comparing its metrics against a group of similar institutions rather than against absolute industry averages. It puts ratios like profitability, capital, and efficiency in context, so differences reflect performance rather than differences in bank size or type.
How are UBPR peer groups defined? Since February 26, 2026, the UBPR assigns each commercial bank to one of 17 standard peer groups based on asset size alone, measured as average assets for the quarter (RCON3368). Number of offices and metropolitan location, which earlier applied to banks under $300 million, are no longer used. Every ratio is reported alongside the peer group average and the bank’s percentile ranking within that group.
Why are percentile rankings more useful than raw ratios? A percentile shows where a bank stands in the distribution of its actual peers. It is self-calibrating for the shared operating environment: if the rate cycle compresses everyone’s margins, a stable percentile rank signals relative resilience. It also surfaces outliers immediately without requiring you to know what the “right” level of each ratio should be.
When should I build a custom peer group? Build one when the standard UBPR group is a poor fit: the subject bank has a distinctive business model, competes in a specific geographic market, or the standard size band is too wide to be meaningful. The goal is to make peers as alike as possible in structure so the comparison isolates genuine performance differences.
What makes two banks good peers? Similar asset size, business model (loan mix, funding profile), geographic market, and charter type. The more alike the peers are on those structural dimensions, the more a difference in the ratios reflects a real performance difference rather than a structural one.
Where does the underlying data come from? FFIEC call reports (FFIEC 031/041/051) filed quarterly with the Federal Reserve, FDIC, and OCC. The UBPR aggregates and presents this data with peer group context. BankRegReports publishes clean, validated versions of the same data through its API, going back more than 25 years. Its bank peer analysis software ranks any bank against its asset-size tier or a custom peer group you build with a free account.
BankRegReports publishes call report, UBPR, FDIC, Federal Reserve, NCUA, and SEC EDGAR data for every U.S. bank and credit union, with peer benchmarks and quarterly history. Look up a bank