CRE Concentration Risk in Banking: A Data Analysis
Commercial Real Estate (CRE) concentration risk remains one of the most significant portfolio challenges facing U.S. banks, particularly community institutions. This analysis examines the regulatory framework, current industry exposure patterns, and actionable assessment tools regulators expect you to employ.
Understanding CRE Concentration Risk
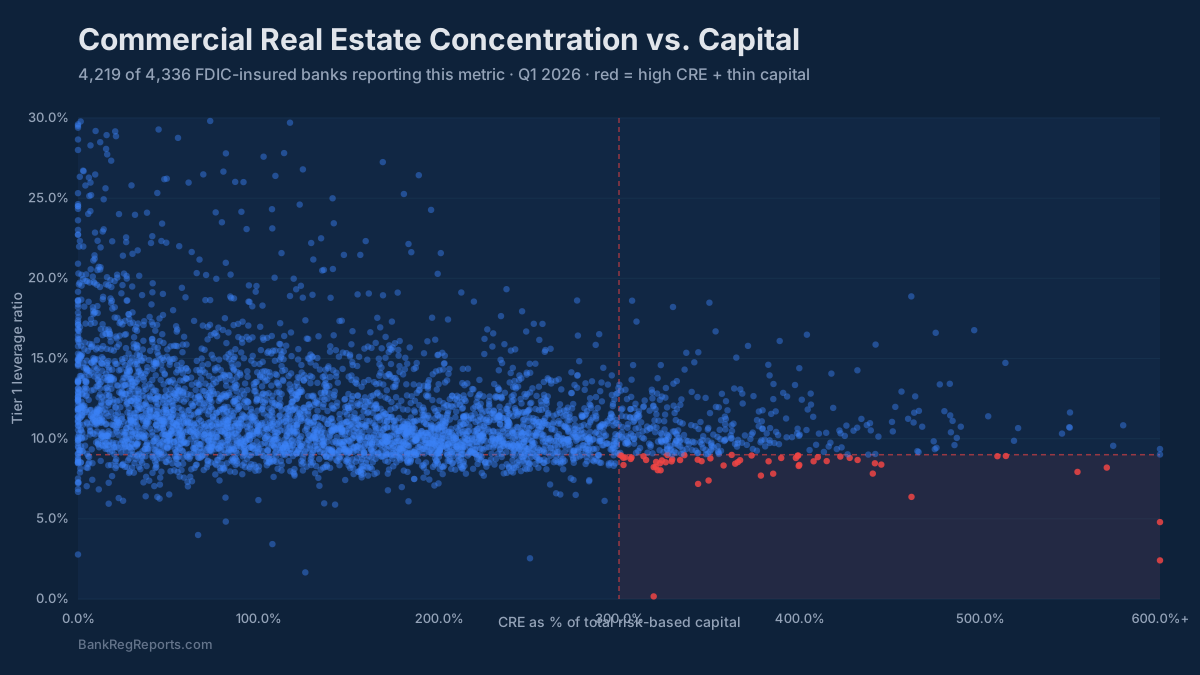
CRE concentration risk is the risk that a bank holds too much commercial real estate debt relative to its capital. Regulators screen for it two ways. The first is total CRE at or above 300% of total risk-based capital with 50% growth over 36 months. The second is construction and land development loans at or above 100%.
Commercial Real Estate (CRE) lending has long been a core part of community bank portfolios. For many regional and smaller institutions, CRE loans represent 40-60% of total credit exposure. That sometimes exceeds regulatory comfort zones by significant margins. And the link between CRE concentration and institutional risk has never been more visible or more scrutinized.
The 2008 financial crisis showed that unchecked concentration risk can turn a seemingly stable portfolio into a threat to the bank’s survival. Nearly two decades later, regulatory agencies have formalized their expectations. Your board must understand three things:
- current CRE exposure;
- stress scenarios;
- the regulatory standards that define acceptable concentration levels.
This post gives a data-driven framework for assessing your bank’s CRE concentration risk. It covers the regulatory thresholds, how to calculate exposure ratios, and the stress testing models examiners expect to see during examination.
The Regulatory Framework: 2006 Interagency Guidance
The Federal Reserve, OCC, and FDIC issued formal CRE concentration guidance in 2006. Later guidance documents refined it. The framework sets two concentration thresholds and a growth criterion:
The 300% Threshold
A bank draws heightened supervisory attention when its CRE loans reach 300% or more of total risk-based capital. The portfolio must also have grown 50% or more over the prior 36 months (see the growth criterion below). This does not mean automatic enforcement action. It signals that concentration levels warrant:
- board-level governance;
- documented risk appetite statements;
- explicit underwriting and stress testing protocols.
What counts as CRE for the 300% metric
Key definition: For the supervisory concentration metric, CRE loans are those where repayment depends on the sale, refinancing, or rental/lease income of the real estate. They are reported on Schedule RC-C (Loans and Lease Financing Receivables) of the call report and include:
- construction and land development loans;
- multifamily loans;
- non-owner-occupied nonfarm nonresidential loans.
This covers office, retail, hospitality, multifamily, industrial, and other income-producing property types.
Loans secured by owner-occupied commercial property are generally excluded from the 300% metric, even though they remain CRE for other purposes. For those loans, repayment comes primarily from the occupying business’s operating cash flow rather than the real estate.
The 100% Threshold for Land Development and Construction
Land development and construction lending faces a stricter threshold: 100% of total risk-based capital. This applies particularly to speculative projects without a long-term take-out commitment. It reflects the higher loss severity in construction phase liquidity events.
The 50% Growth Criterion
In short, a bank is flagged for heightened supervisory review in either of two cases:
- construction and land-development loans are at or above 100% of total risk-based capital; or
- total CRE is at or above 300% of capital and has grown 50% or more over 36 months.
The 2006 guidance does not evaluate the 300% total-CRE ratio in isolation. Its second supervisory criterion is conjunctive: total CRE at or above 300% of total risk-based capital AND CRE loan growth of 50% or more over the preceding 36 months. Both conditions must be met.
A bank can sit above 300% without triggering this criterion if its portfolio has not grown rapidly. Rapid growth layered on top of a high concentration is what draws heightened review. It signals that underwriting discipline, portfolio monitoring, and risk management infrastructure may not have kept pace with origination volume.
The construction and land-development screen (100% of total risk-based capital) is a separate, standalone test.
Beyond the Numbers: Qualitative Expectations
Regulators do not stop at threshold analysis. Under the 2006 guidance and later examination handbooks, banks exceeding these levels must show:
- Written risk appetite statement defining maximum acceptable CRE concentration
- Board-approved concentration limits by property type
- Market analysis supporting underwriting decisions in the relevant geographies
- Stress testing showing portfolio resilience under adverse scenarios
- ACL (Allowance for Credit Losses) methodology that reflects CRE-specific risk
- Strong underwriting standards including debt service coverage ratio (DSCR) minimums, loan-to-value (LTV) caps, and reserve requirements
Current State of CRE Concentration Across U.S. Banks
Recent call report data reveals a bifurcated banking system in CRE exposure:
Distribution by Bank Size
Community banks ($1B–$10B assets): CRE concentration runs highest in this cohort. At June 30, 2026, 20% of these banks reported non-owner-occupied CRE above 300% of tier 1 capital plus the allowance, and the median bank sat at 224%. They tend to have limited geographic diversification and depend heavily on local commercial real estate cycles.
Regional banks ($10B–$50B assets): The median is close to the community bank cohort (221%), but fewer banks cross the line. At June 30, 2026, 16% were above 300%, helped by more geographic and property-type diversification.
Large banks ($50B+ assets): CRE concentration is the lowest of the three cohorts. The median is 88%, and 6% of banks were above 300% at June 30, 2026, reflecting much larger C&I, consumer and securities books. (Banks under $1 billion: median 101%, 6% above 300%. All figures are BankRegReports analysis of Call Report data.)
Geographic Concentration Patterns
CRE concentration risk is not evenly spread. States with concentrated commercial real estate markets (Florida, Texas, California, New York) show disproportionately high exposure levels among regional banks. Smaller banks in secondary markets often lack the scale to diversify across property types. That leaves them exposed to localized commercial real estate downturns.
Property Type Breakdown
Call report Schedule RC-C does not split CRE by office, retail, hotel or industrial. It breaks real estate loans into construction and land development, farmland, 1-4 family residential, multifamily, and nonfarm nonresidential (owner-occupied and other). The property-type view below comes from a bank’s own loan system:
- Office: The most distressed category post-pandemic. Office vacancy rates exceed historical averages in most markets, with limited conversion-to-residential potential. Many banks have not fully repriced office risk.
- Retail: Structural decline continues, though grocery-anchored and necessity-based retail show better fundamentals than traditional enclosed shopping centers.
- Hospitality: Highly cyclical; many hotels carry elevated leverage from pandemic-era distress sales and refinancings.
- Multifamily: The strongest property type historically. New supply deliveries, potential oversupply in many markets, and changing resident preferences still create pockets of risk.
- Industrial/Warehouse: Fundamentally sound, though e-commerce normalization has slowed net absorption in some markets.
Why CRE Concentration Matters Now
Three converging forces have elevated CRE concentration risk to the top of regulatory and market agendas:
1. Office Market Distress
Post-pandemic office use remains structurally lower than pre-2020 levels. Remote work policies have permanently reduced demand in secondary and tertiary markets. More critically, many office loans originated during the 2012-2018 bull market now face maturity at depressed valuations. Refinancing is increasingly unavailable at original underwriting assumptions.
Banks that underpriced office risk, or over-concentrated portfolios in office-dependent markets, face mounting nonperforming asset pressure.
2. The Current Refinancing Wave
Billions of CRE debt is maturing now, much of it originated at lower rates. With rates well above the levels at which much of it was originated, loan extension and modification have become the default refinancing path. This extends the tail risk in your portfolio and creates moral hazard incentives.
Regulators are intensely focused on loan modification practices. Examiners expect documentation showing that modified loans reflect current market conditions, not artificially maintained assumptions.
3. Regulatory Pressure and Examination Intensity
CRE risk has moved from a periodic examination topic to a standing supervisory priority. The Federal Reserve’s supervision reports since 2023 have explicitly highlighted CRE concentration, office exposure, and commercial real estate stress. OCC guidance mirrors this focus.
Your bank’s CRE risk management framework will be examined with increasing scrutiny.
How to Assess Your Bank’s CRE Concentration Risk
Step 1: Calculate Core Concentration Ratios
CRE loan concentration ratio = Total CRE loans / Total regulatory capital
This is your starting point. If this ratio is at or above 300% and total CRE has grown 50% or more over the prior 36 months, you meet the guidance screen. Above 300% without that growth, you are still at the level examiners watch.
Data source: Schedule RC-C, Part I, Section A (Loans and Leases Secured by Real Estate) and Schedule RC-R (Regulatory Capital Components)
Example calculation:
- Total CRE loans: $450 million
- Total regulatory capital (Tier 1 + Tier 2): $120 million
- Concentration ratio: $450M / $120M = 375%
- Total CRE loans 36 months earlier: $280 million, so growth of 61%
This bank is above 300% and grew CRE more than 50% over 36 months, so it meets the guidance screen and needs documented governance and risk management controls.
Step 2: Decompose by Property Type
Extract loans by property type from your loan system (Schedule RC-C does not carry this split):
| Property Type | Loan Balance | % of Total CRE | % of Capital |
|---|---|---|---|
| Office | $120M | 26.7% | 100% |
| Retail | $85M | 18.9% | 70.8% |
| Multifamily | $120M | 26.7% | 100% |
| Industrial | $75M | 16.7% | 62.5% |
| Hotel/Hospitality | $40M | 8.9% | 33.3% |
| Other | $10M | 2.2% | 8.3% |
| Total | $450M | 100% | 375% |
This breakdown reveals concentration within concentration. Office at 100% of capital is material; combined with other property types, it drives total risk.
Step 3: Assess Geographic Concentration
Pull loan data by metropolitan area or state (if your systems support it):
- Which cities/regions represent more than 20% of your CRE portfolio?
- What is the economic diversity within those markets?
- Are you over-concentrated in economically cyclical industries (tourism, energy, aerospace)?
Geographic concentration compounds property type risk. A bank with 40% of its CRE exposure in one city is far more vulnerable than a geographically dispersed peer.
Step 4: Implement Stress Testing Framework
Regulators expect documented stress testing. A basic framework includes:
Scenario 1: 15% Decline in CRE Values
- Impact on LTV ratios: Which loans move above regulatory LTV limits?
- Impact on DSCR: Which borrowers show cash flow stress?
- Expected loss severity: What reserve level is appropriate?
Scenario 2: Economic Recession (3-5% GDP decline)
- Office: Assume 10% vacancy increase, 5% rent decline
- Retail: Assume 15% vacancy increase, 8% rent decline
- Multifamily: Assume 7% vacancy increase, 3% rent decline
- Hotel: Assume 20% occupancy decline, 10% ADR decline
Scenario 3: Rate Shock (200 basis point increase)
- Impact on borrower cash flows
- Refinancing availability and impact
- Duration of payment shock before default
Document these scenarios in writing. Your examination team will ask to see them.
Step 5: Benchmark Against Peer Group
Use call report data to compare your concentration ratios to peer institutions:
- What is the median CRE concentration for banks your size in your region?
- How does your office concentration compare?
- Are you an outlier? If so, is that by design (intentional risk appetite) or drift (unmanaged concentration)?
Peer group analysis provides context for your risk positioning. Significant positive outliers attract examiner attention.
What Regulators Are Looking For in the Examination Room
When examiners review your CRE portfolio, they are evaluating five core dimensions:
1. Governance and Risk Appetite
Documentation expected:
- Board-approved risk appetite statement defining maximum acceptable CRE concentration by property type
- Written CRE lending policy with underwriting standards (minimum DSCR, maximum LTV, reserve requirements)
- Board minutes demonstrating active monitoring and discussion of concentration levels
- Management information system (MIS) reports provided to the board on a regular cadence (at minimum quarterly)
Red flags:
- No written CRE policy
- Concentration limits not approved by the board
- No documentation of concentration trending or stress analysis
- Management unable to articulate the bank’s CRE risk appetite
2. Underwriting Standards
Examiners pull a sample of CRE loans for detailed review. They are looking for:
- DSCR analysis: Is debt service coverage at least 1.25x for stabilized properties?
- LTV validation: Are loan-to-value ratios within policy for the property type (typically 65-75% for office, 70-80% for multifamily)?
- Market analysis: Evidence that underwriting reflected accurate market conditions at origination
- Guarantor support: Personal guarantees and guarantor net worth documentation
- Reserve requirements: Policy-consistent reserves against loss severity
Deficiency pattern: Multiple loans with DSCR below 1.10x, LTV above 80%, or weak guarantor support triggers concentration risk conclusions.
3. Market Analysis and Monitoring
Regulators expect banks to understand the markets in which they are concentrated:
- Can your lending team articulate the current vacancy rate, rent trends, and economic drivers in your top CRE markets?
- How frequently do you obtain updated market analysis (at least annually; quarterly for stressed properties)?
- Do you have thresholds for market analysis refresh? (e.g., “Annual update required; immediate update if vacancy reaches 15%”)
4. Stress Testing and Scenario Analysis
Documentation of stress testing methodology, assumptions, and results is now a standard examination deliverable. Examiners want to see:
- Written stress testing policy
- Documented scenarios (recession, value decline, rate shock)
- Results quantifying impact on nonperforming assets, loss rates, and capital ratios
- Board discussion of stress testing results and implications for risk limits
This is not optional. If you are above the 300% threshold and lack formal stress testing documentation, examiners will cite deficiencies.
5. Allowance for Credit Losses (ACL) and Reserve Adequacy
The ACL methodology must reflect CRE-specific loss severity. The current expected credit losses (CECL) framework (ASC 326) replaced the former ALLL incurred-loss model. Under CECL, examiners evaluate:
- Historical loss rates by property type
- Current economic conditions and forward-looking adjustments
- Specific reserves against troubled CRE loans
- Lifetime expected loss estimates that differentiate CRE by property type and risk profile
If your ACL reserve level is significantly lower than peer institutions in your peer group, examiners will question the adequacy.
Managing CRE Concentration Risk
Beyond regulatory compliance, leading banks employ these practices:
Establish Concentration Limit Frameworks
Define maximum acceptable concentration levels for:
- Total CRE as % of capital (typically 250-350% depending on risk appetite)
- Each major property type (office, retail, multifamily, industrial, hospitality)
- Geographic markets (no single market >20-25% of CRE portfolio)
- Borrower or guarantor (no single entity >5-10% of portfolio)
These limits should be approved by the board and monitored monthly by management.
Implement Tiered Underwriting Standards
Different property types warrant different standards:
| Property Type | Minimum DSCR | Maximum LTV | Key Risk Drivers |
|---|---|---|---|
| Multifamily (stabilized) | 1.15x | 75% | Occupancy, rent growth |
| Office (Class A) | 1.25x | 70% | Occupancy, market trends |
| Office (Class B/C) | 1.35x | 65% | Structural vacancy risk |
| Industrial | 1.20x | 75% | Lease-up risk, market absorption |
| Retail | 1.25x | 65% | Store closures, format risk |
| Hotel | 1.30x | 70% | Occupancy, ADR volatility |
Higher-risk property types and weaker markets justify tighter underwriting.
Create Market Dashboards
Develop monthly or quarterly metrics tracking:
- Vacancy rates in your top markets
- Rent growth/decline trends
- Cap rate movement
- New supply pipeline
- Loan modification and extension rates
Share these dashboards with the board. They provide early warning of market stress and justify proactive portfolio management.
Strengthen Loan Modification Governance
With the refinancing wall ahead, modification practices are under intense scrutiny. Implement:
- Modification triggers: Define when a loan automatically goes to a structured modification review (e.g., loan approaching maturity, declining market conditions, borrower distress)
- Re-underwriting requirements: Modifications must reflect current market values, updated borrower financials, and realistic future projections
- Extension caps: No loan should be extended indefinitely; set maximum extension periods (typically 2-3 years) to force ultimate resolution
- Board reporting: Monthly reports on modifications by property type and modification terms
Use Peer Data for Benchmarking
Subscribe to peer group analysis tools or access Federal Reserve data to:
- Track how your concentration ratios trend relative to peers
- Identify emerging risks in property types or markets
- Justify board decisions (“We are reducing office concentration because peer banks in our market are also tightening office exposure”)
How BankRegReports Tracks CRE Concentration Risk
BankRegReports is purpose-built to extract, analyze, and benchmark CRE concentration data from call reports:
Automated Concentration Ratio Calculation
BankRegReports already holds every FDIC-insured institution’s call report history, so there is nothing to upload. Look up a bank and the platform shows:
- Total CRE loans (Schedule RC-C)
- Regulatory capital (Schedule RC-R)
- Concentration ratio
- Comparison to its peer group
No manual calculation required.
Property Type Decomposition
The platform breaks CRE loans into the categories the Call Report actually carries:
- Construction and land development
- Multifamily
- Nonfarm nonresidential, owner-occupied
- Nonfarm nonresidential, other
- Loans to finance CRE not secured by real estate
See your concentration by category alongside peer benchmarks. Office, retail, hotel and industrial splits are not in the Call Report, so that view has to come from your own loan system.
Inputs for Your Stress Testing
The platform provides the clean, standardized concentration and loan-category data that feed a stress test: current balances, ratios, and peer context. You can then run value-decline, recession, and rate-shock scenarios in your own models.
Trend Analysis
Track your CRE concentration over quarters and years:
- Is office concentration increasing or declining?
- How has your total CRE ratio moved?
- What is the trajectory relative to your peer group?
Peer Benchmarking Reports
See how your CRE concentration compares to:
- Banks your exact asset size
- Banks in your geographic region
- Banks in your market
- Best-quartile and worst-quartile performers
Outlier identification helps your board set realistic and justifiable risk limits.
Frequently Asked Questions
Q: What is the difference between the 300% and 100% CRE concentration thresholds?
A: The 300% screen applies to total CRE loans as a percentage of total risk-based capital, and it works together with growth. A bank meets it only when total CRE is at or above 300% and the CRE portfolio has grown 50% or more over the prior 36 months.
The 100% screen applies on its own to land development and construction loans, which carry higher loss severity due to the absence of stabilized cash flows. Banks with construction exposure at or above 100% of capital face heightened scrutiny even if total CRE is below 300%. Both are screens for supervisory attention, not limits.
Q: How do I know if my bank’s CRE concentration is a problem?
A: The regulatory guidance indicates that a bank meeting its screens (total CRE at or above 300% of total risk-based capital with 50% growth over 36 months, or construction at or above 100%) should have board-approved risk governance, documented underwriting standards, and stress testing.
However, “problematic” is context-dependent. A well-diversified regional bank at 320% concentration with strong underwriting may pose less risk than a community bank at 280% with concentration in a single distressed market. Use peer benchmarking and stress testing results to determine whether your concentration reflects acceptable risk or requires portfolio adjustment.
Q: What should a stress test for CRE concentration include?
A: A basic stress test should model at least three scenarios: (1) a value decline scenario (10-15% reduction in commercial real estate values), (2) an economic recession scenario (with property-type-specific assumptions for vacancy and rent), and (3) a rate shock scenario (200+ basis point increase in rates).
For each scenario, calculate the impact on loan-to-value ratios, debt service coverage ratios, and the expected increase in nonperforming assets. Document assumptions and results for board review.
Q: How often should I update my CRE risk management policy?
A: Annual review is a minimum; quarterly review and update is recommended practice. At minimum, update the policy when: (1) concentration limits are breached, (2) market conditions materially change, (3) regulatory guidance is updated, or (4) the bank enters a new market or exits existing concentration. Your board should affirmatively review and approve the policy at least annually.
Q: What is the most common CRE concentration deficiency examiners find?
A: Lack of documented stress testing and scenario analysis. Many banks have concentration policies and underwriting standards but fail to formally document how their portfolio would perform under adverse scenarios. Examiners expect written stress testing methodologies, documented results, and board discussion. This is now a standard examination finding for banks above the 300% threshold without formal stress testing documentation.
Q: How should I handle CRE loans in modification due to the refinancing wall?
A: Re-underwrite modified loans to current market conditions, not original assumptions. Obtain current appraisals or market analysis; update borrower financials; stress-test the borrower’s ability to service debt if rates or values decline further. Document the modification rationale in the file. Avoid extending loans indefinitely; cap extensions at 24-36 months to force ultimate resolution (payoff, sale, or structured workout). Report modifications and extension rates to the board monthly.