The bank-data edge, before it's priced in.

Screen every US bank for stress signals, uninsured deposits, and CRE concentration, and, on the Pro plan, export 26 years of standardized per-bank history into your model.

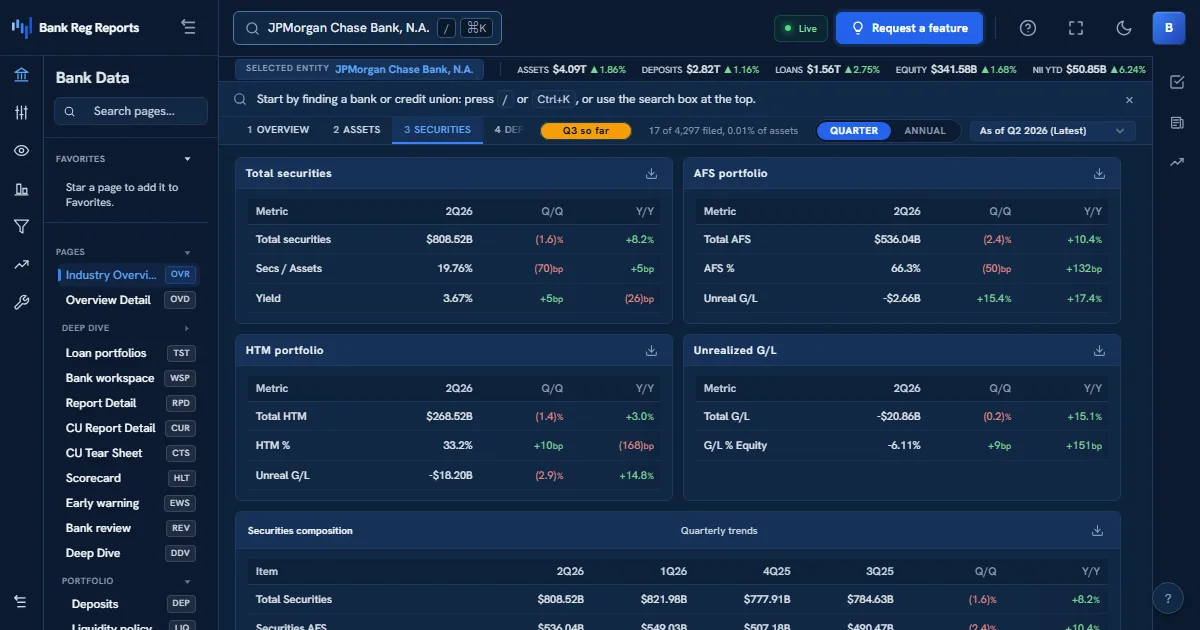
BankRegReports securities view showing AFS and HTM portfolios, unrealized gains and losses, the maturity and repricing ladder, and the unrecognized HTM gain or loss for a bank.

For the buy side, the edge in bank exposure lives in the regulatory data before it reaches the tape. BankRegReports lets asset managers, hedge funds, and private equity screen the entire universe of FDIC-insured banks on the metrics that drive valuation and risk, capital, funding, credit quality, and unrealized securities marks, and, on the Pro plan, export per-bank history straight into a model.

The challenge

  • Bank fundamentals are scattered across FFIEC bulk files, UBPR pages, and 10-Ks, none of them model-ready.
  • Screening the whole sector on a single factor (deposit runoff, CRE concentration, AOCI) is impractical by hand.
  • The signals that move bank equities show up in trends across quarters, not a single snapshot.

How BankRegReports helps

Sector-wide screening

Filter the full universe of banks on capital, profitability, funding, growth, and credit metrics to build a long or short shortlist in seconds.

See pricing →

Stress signals and tails

Ranking pages surface the extremes (highest Texas Ratio, lowest CET1, highest uninsured-deposit share), and the CRE concentration screener ranks every bank against the supervisory screens, so the tails of the distribution find you.

View rankings →

Model-ready history

Standardized quarterly history back to Q1 2000, with per-bank CSV export on the Pro plan, so you can model full credit cycles, not just the latest print.

Check data coverage →

How asset managers put it to work

Typical workflows, from the first search to a client-ready or board-ready output.

Turn a macro view into a shortlist

You have a thesis on deposit flight, CRE stress, or duration risk and need the names across the whole universe that express it. You screen every bank on the driving factor and rank the extremes.

  1. Filter all FDIC-insured banks on the factor behind the thesis.
  2. Rank to surface the tails, longs on one end, shorts on the other.
  3. Open each name's profile; on the Pro plan, export its metric history to CSV for the book.
Underwrite the AOCI and duration exposure on a name

A regional bank screens cheap, but the unrealized securities marks may hollow out the capital cushion. You quantify the duration and AOCI exposure before it reprices.

  1. Open the securities view for AFS/HTM marks and the unrecognized HTM loss.
  2. Read the maturity-and-repricing ladder for rate sensitivity.
  3. Weigh the mark against tangible common equity for the true cushion.

Backtest a signal across a full cycle

A factor only earns its place after it survives a credit cycle, not a single quarter. You pull decades of standardized panels to test it properly.

  1. Select the metric and universe for the backtest.
  2. On the Pro plan, export each bank's standardized quarterly history to CSV.
  3. Check glossary definitions for breaks such as CECL adoption before you model drawdowns.

See it in action

The same views you'll work in, on real FDIC-insured banks, refreshed every quarter.

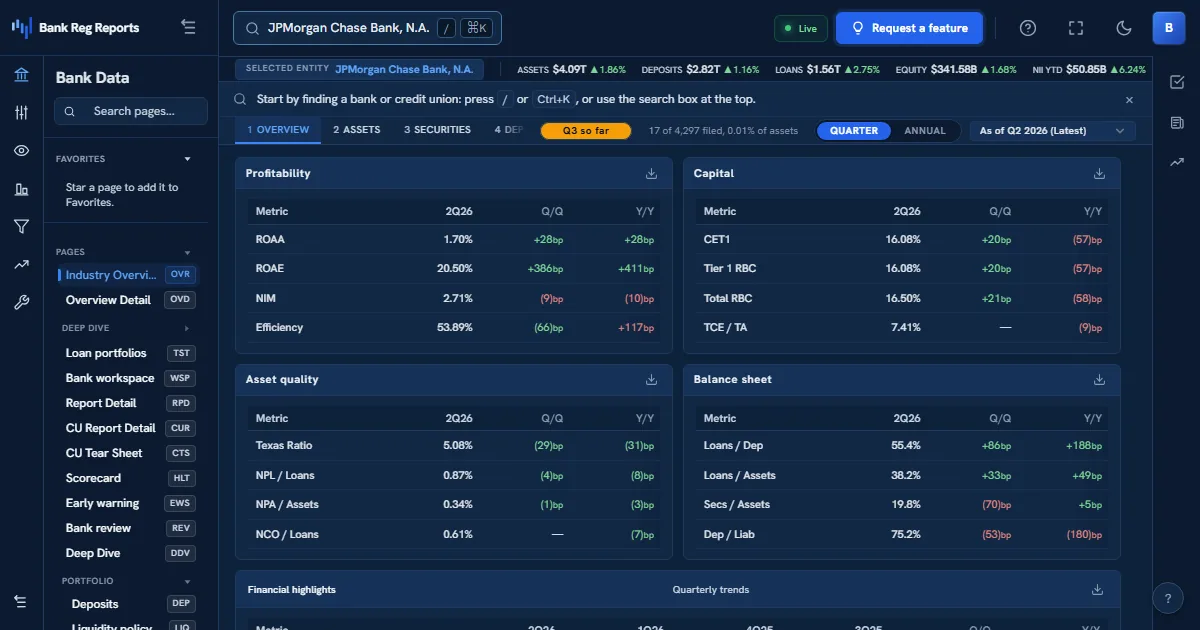
BRR Terminal overview with profitability, capital, and asset-quality ratio panels plus a total-assets-versus-ROAA trend chart for a bank.

Every fundamental on one screen

ROAA, ROAE, NIM, efficiency, CET1 and Texas Ratio, each with quarter-over-quarter and year-over-year deltas and multi-quarter trends, drawn from 892 standardized measures per bank: the whole fundamental picture before it reaches the tape.

See pricing →

Frequently asked questions

Does it cover unrealized securities losses?

Yes. The securities views surface AOCI and held-to-maturity versus available-for-sale positioning (the exposure that became central to bank risk after 2022) for every institution.

Can I export the full history for my own model?

Yes, on the Pro plan. Pro exports per-bank metric histories to CSV (up to 40 quarters and 20 banks at a time) and the full ranked list of any prebuilt screen; the rankings pages do not export. Every metric is defined in the glossary, so check it for breaks such as CET1 starting in 2015 and CECL adoption from 2020.

Can I screen for a single-factor thesis like CRE concentration or uninsured deposits?

Yes. The risk screeners rank every bank on CRE concentration, construction concentration, uninsured deposits, and AOCI burden, and the ranking pages cover capital, credit quality, and profitability, so a shortlist that fits the thesis comes back in seconds.

How much history is available for backtesting and credit-cycle work?

Standardized quarterly panels reach back to Q1 2000, more than 26 years, across every FDIC-insured bank, so you can model full credit cycles rather than the latest print.

Built for other roles too

See it on your bank

Every FDIC-insured institution, 26+ years of standardized data, one search away.