
Credit risk monitoring for a portfolio of banks.

Watch nonaccrual loans, charge-offs, reserve coverage and CRE concentration across every bank you hold or lend to, with alerts when a filing moves.

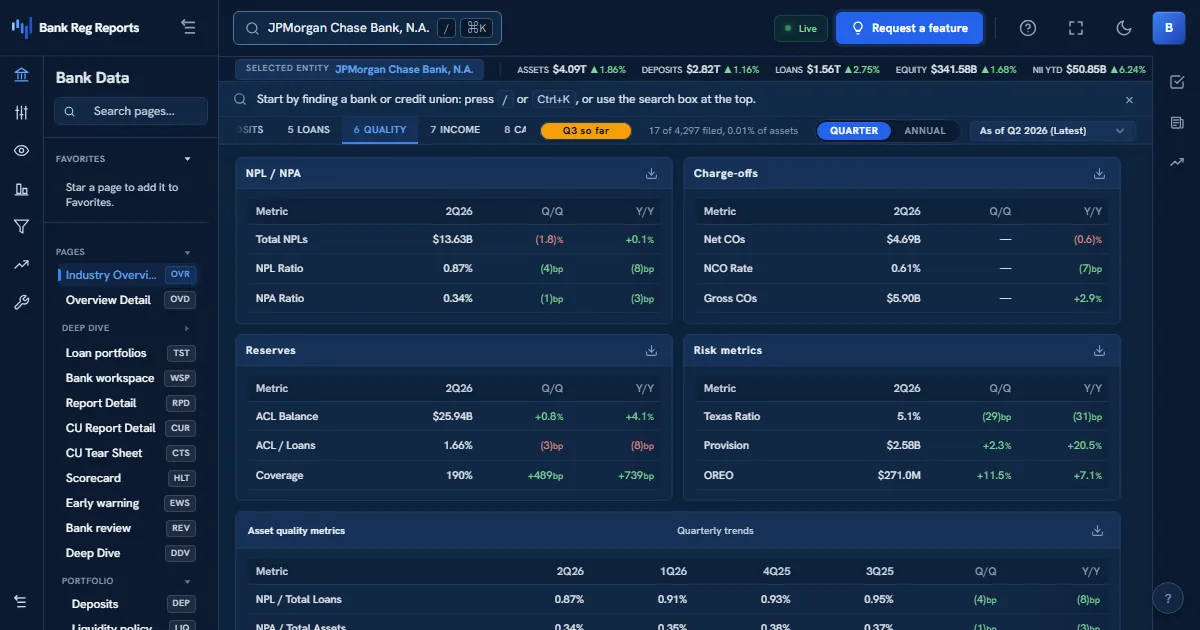
BankRegReports asset-quality view for a bank showing NPL and NPA ratios, net charge-offs, allowance balance and coverage, Texas ratio, provision and OREO with quarter-over-quarter and year-over-year changes.

Credit risk monitoring for a portfolio of banks means watching the loan books behind each exposure: nonaccrual and past due loans, net charge-offs, the allowance against them and concentrations in commercial real estate. BankRegReports reads those from each bank's quarterly call report, puts every bank you follow on one watchlist with warning flags, emails an alert when a ratio crosses a level you set, and ranks every bank on the same measures in public screeners.

The challenge

  • Credit deterioration shows up in one loan portfolio first, and a bank-wide ratio hides which one.
  • Checking twenty banks' filings by hand each quarter means the one that changed is found late.
  • A concentration or a falling reserve means little without the bank's peers and its own trend.

How BankRegReports helps

One board for every bank you follow

The portfolio monitor shows every bank on your watchlist on one screen: warning flags and the core capital, credit and funding ratios, so the bank that changed stands out.

Open the portfolio monitor (sign-in required) →

CRE concentration, ranked

The CRE concentration screener ranks every bank by regulatory commercial real estate against total capital, beside the 300% supervisory screen.

Open the CRE screener →

Alerts when a filing moves

Set a threshold on a credit or capital ratio for any bank on your watchlist and get an email when a new filing crosses it.

See alerts →

How credit risk teams put it to work

Typical workflows, from the first search to a client-ready or board-ready output.

Catch the deteriorating bank before the quarter's call

You hold debt of, or lend to, thirty banks. You want to know within days of a filing which loan books weakened, not at year-end.

  1. Add the banks to a watchlist and open the portfolio monitor.
  2. Set alert thresholds on the nonaccrual rate and allowance coverage.
  3. When an alert fires, open the bank's asset-quality view for the portfolio behind it.

Frequently asked questions

What does bank credit risk monitoring track?

The quality of a bank's loan book as reported each quarter: nonaccrual and past due loans by portfolio, net charge-offs, the allowance for credit losses and its coverage of problem loans, and concentrations such as commercial real estate against capital.

Where does the data come from?

Each bank's quarterly FFIEC call report: Schedule RC-N for past due and nonaccrual loans, RI-B for charge-offs and the allowance, and RC-C for the loan mix behind concentrations.

Is monitoring free?

Yes. Watchlists, the portfolio monitor, threshold alerts by email and the public screeners are free. Pro adds CSV exports of screens and Excel tearsheets, at the price published on the pricing page.

Does this show a bank's CAMELS rating?

No. CAMELS ratings are confidential supervisory information. The scores here are our own, built from public filings and organized under the CAMELS headings; they are not regulatory ratings.
See it on your bank

Every FDIC-insured institution, 26+ years of standardized data, one search away.