
Bank analytics your board can actually read.

Plain-English metrics, peer context, and quarterly scorecards that turn a stack of regulatory filings into a five-minute read.

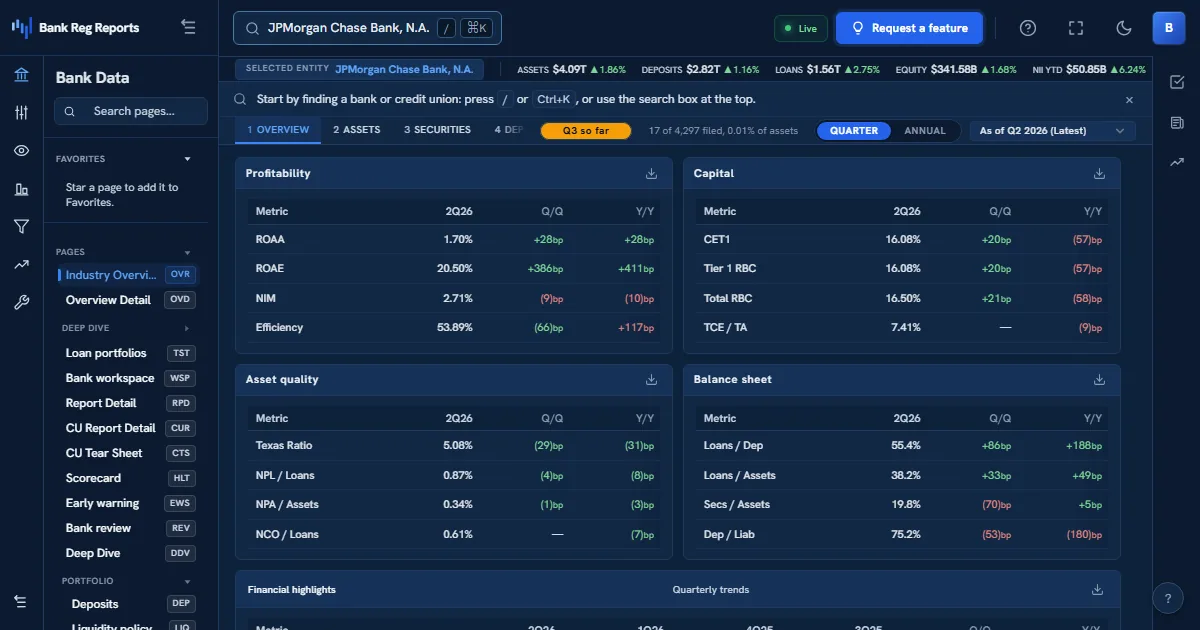
BRR Terminal overview showing capital, earnings, and asset-quality ratio panels with quarter-over-quarter direction and a total-assets trend for a bank.

Board members are accountable for a bank's safety and soundness without necessarily being career bankers. BankRegReports presents the same public regulatory data examiners also start from (examiners add confidential exam findings no outside tool can see): capital, asset quality, earnings, liquidity, in scorecards and peer comparisons that make trends obvious and questions easy to ask.

The challenge

  • Regulatory packets are dense and assume fluency in call report schedules.
  • It's hard to tell whether a ratio is normal or a red flag without peer context.
  • Directors need to spot a deteriorating trend before it becomes an exam finding.

How BankRegReports helps

Quarterly scorecards

A single view of capital, asset quality, earnings, and liquidity with quarter-over-quarter direction for each.

See pricing →

Peer context on every number

Each metric is shown against a relevant peer group, so 'is this good?' has an immediate, defensible answer.

Compare banks side by side →

Definitions in plain English

Every ratio links to a glossary entry with the formula, why it matters, and, where one exists, the threshold that triggers supervisory attention.

Open the glossary →

How board members put it to work

Typical workflows, from the first search to a client-ready or board-ready output.

Read the quarterly packet in five minutes

You're a director without a career-banking background, and the board packet assumes fluency in call report schedules. You get the same regulatory data in a scorecard that makes the trend obvious.

  1. Open your bank's scorecard: capital, asset quality, earnings, liquidity in one view.
  2. Read the quarter-over-quarter direction arrows to see what moved.
  3. Tap any ratio you don't recognize for a plain-English definition and its healthy range.

Ask a sharper question in the meeting

A ratio looks off but you're not sure whether it's a problem or normal for the cycle. Peer context turns a vague worry into a specific, answerable question for management.

  1. Find the metric flagged against its peer group (and, for capital, its regulatory minimum).
  2. Check your bank's percentile rank versus similar institutions.
  3. Bring the specific gap (not a hunch) to management for an explanation.

Track a concern across quarters

Last quarter you flagged a rising concentration or a slipping margin. You want to confirm whether management's fix is working before the next exam cycle.

  1. Pull the multi-quarter trend for the metric you raised.
  2. Confirm the direction reversed, or that it's still drifting.
  3. Document the peer-benchmarked read for the minutes.

See it in action

The same views you'll work in, on real FDIC-insured banks, refreshed every quarter.

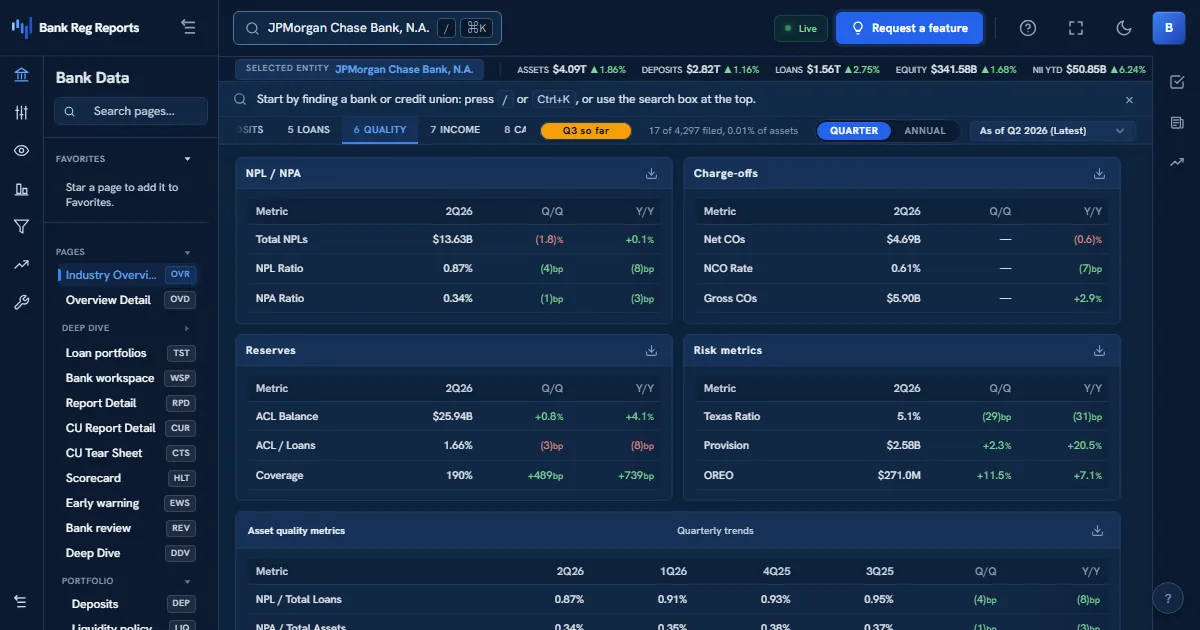
BankRegReports asset-quality view showing noncurrent-loan and NPA ratios, net charge-offs, reserve coverage, the Texas Ratio, and an NPL trend for a bank.

Spot a deteriorating trend before the exam

Noncurrent loans, net charge-offs, reserve coverage, and the Texas Ratio with the multi-quarter trend, benchmarked against peers, so a director can ask the right question a quarter before it becomes an exam finding.

Compare banks side by side →

Frequently asked questions

Do I need a finance background to use this?

No. Metrics are presented with plain-English definitions and peer context, and every ratio links to a glossary entry explaining what it means and what level is healthy.

Can I see how our bank compares to similar institutions?

Yes. Every metric is benchmarked against a peer group, with your bank's percentile rank shown so deviations stand out. Use the standard peer groups or build your own custom peer groups, on any account.

What should a director look at first each quarter?

The scorecard groups public metrics under the same headings examiners use (it does not estimate the confidential CAMELS rating): capital adequacy (CET1, Tier 1 leverage), asset quality (noncurrent loans, net charge-offs, reserve coverage), earnings (ROA, ROE, NIM, efficiency), and liquidity, each with quarter-over-quarter direction and peer context, so a five-minute read tells you whether anything is trending the wrong way.

How do I know if a ratio is a red flag?

Every ratio is shown against its peer group, and capital ratios are also shown against the prompt corrective action thresholds, so 'is this normal?' has an immediate, defensible answer instead of a judgment call.
Built for other roles too

See it on your bank

Every FDIC-insured institution, 26+ years of standardized data, one search away.